The Bloomberg Aggregate Bond Index was created by Lehman Brothers in the early-1980s to offer investors a benchmark for the investment grade taxable bond market.1
The index is made up of mostly Treasuries, corporates, mortgage-back securities and asset-back securities covering more than 10,000 fixed income securities in total.
The Agg is now the benchmark most active fixed income managers measure themselves against. It also acts as the proxy for most total bond market index funds.
Lehman later backfilled historical data, so the index has an inception date of 1976.
Since that inception date, the returns over the past 5 and 10 years are about as bad as they’ve ever been.
These are the rolling 5 year returns for the Agg through the end of August:
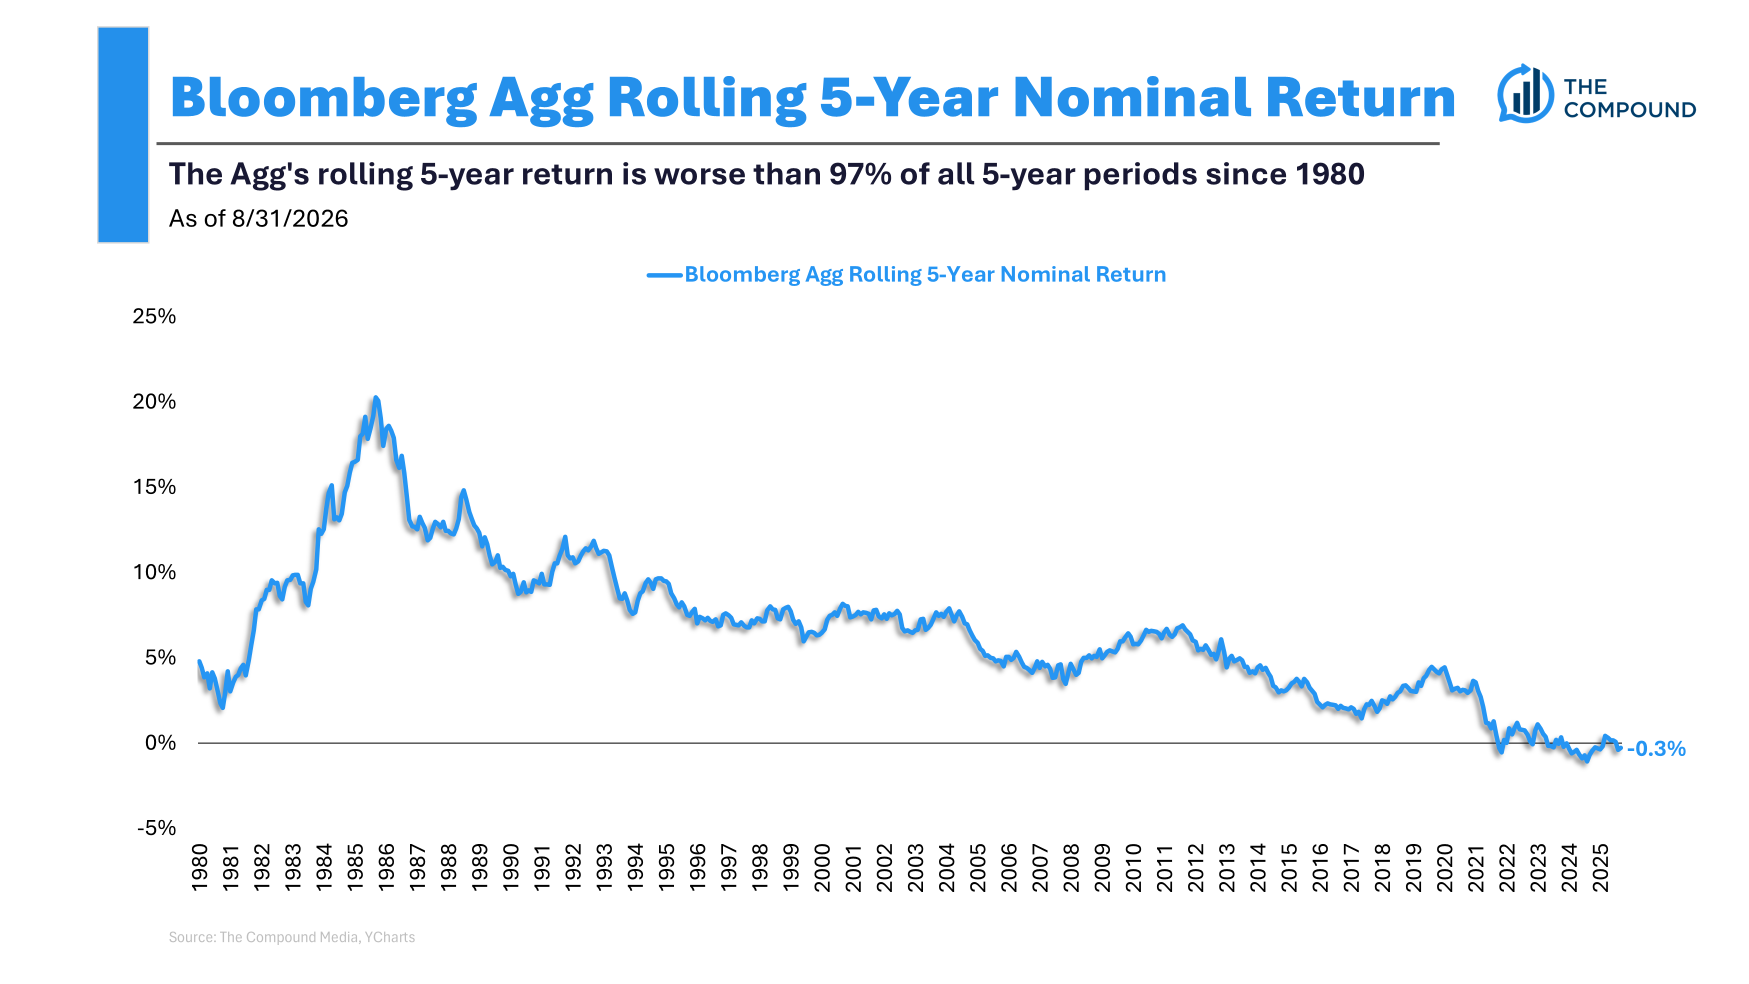
This cycle is the first time in the history of the index there have been negative 5 year returns.
Now here are the rolling 10 year returns:
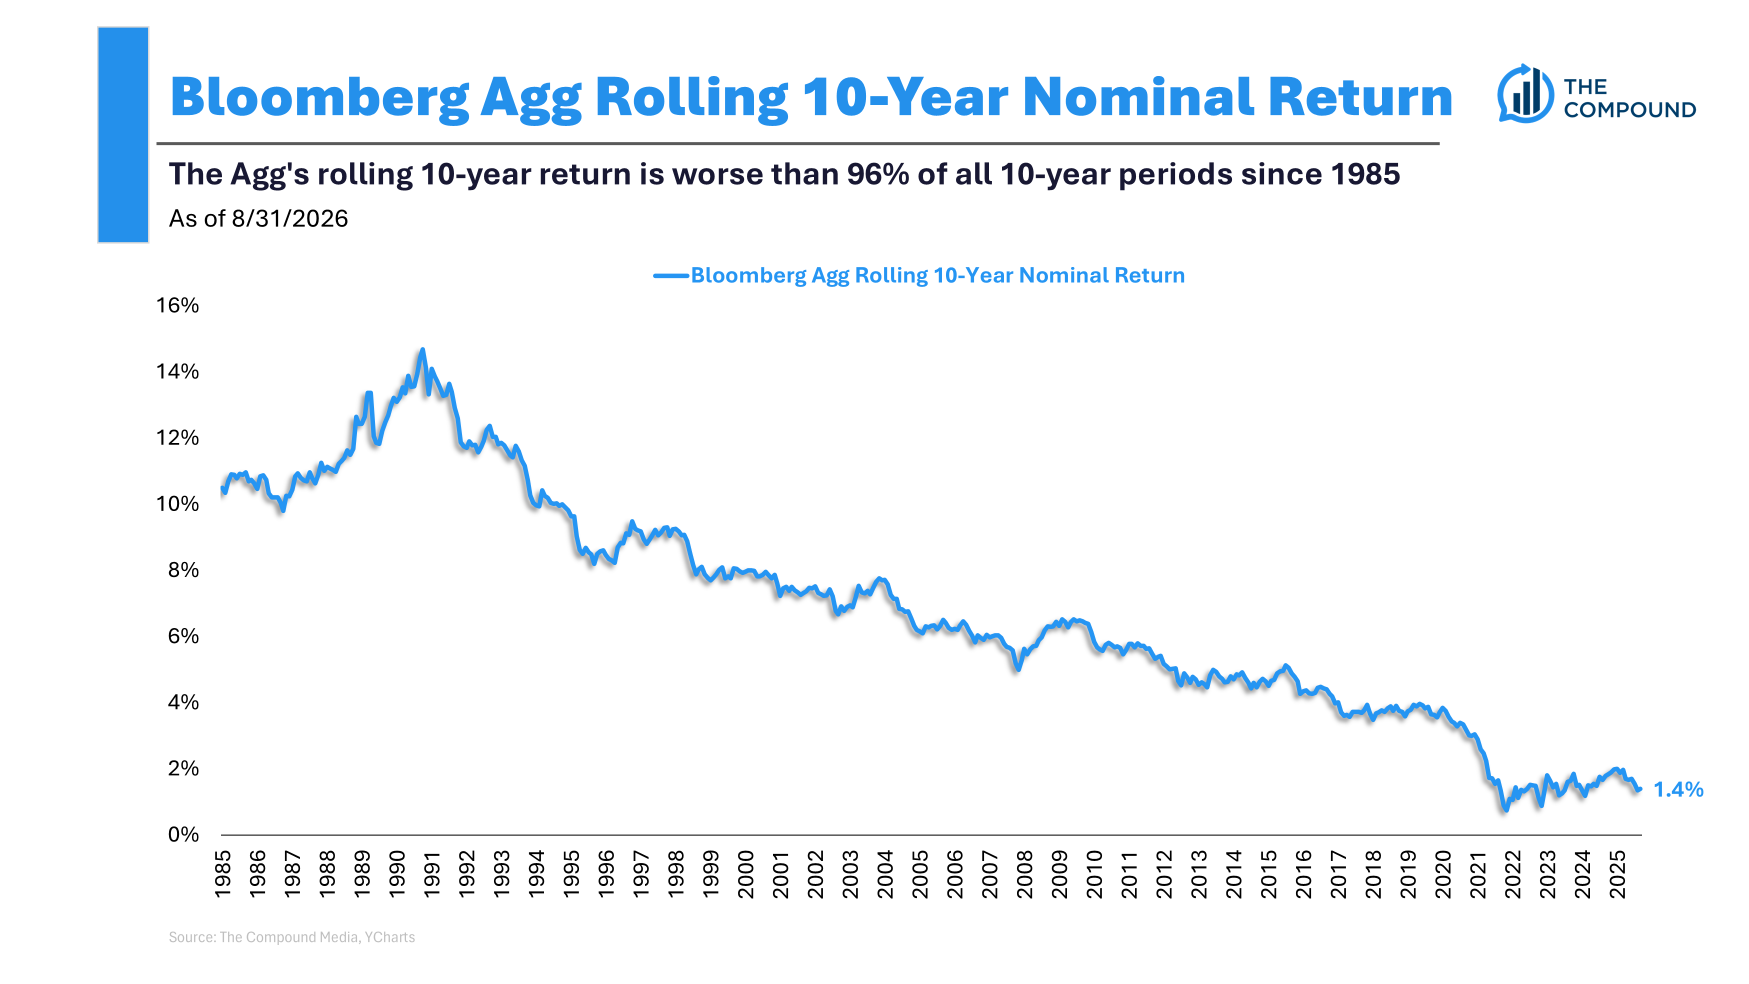
They are positive but but bond investors were close to a lost decade during the 2022 bear market.
Things are even worse after accounting for inflation:
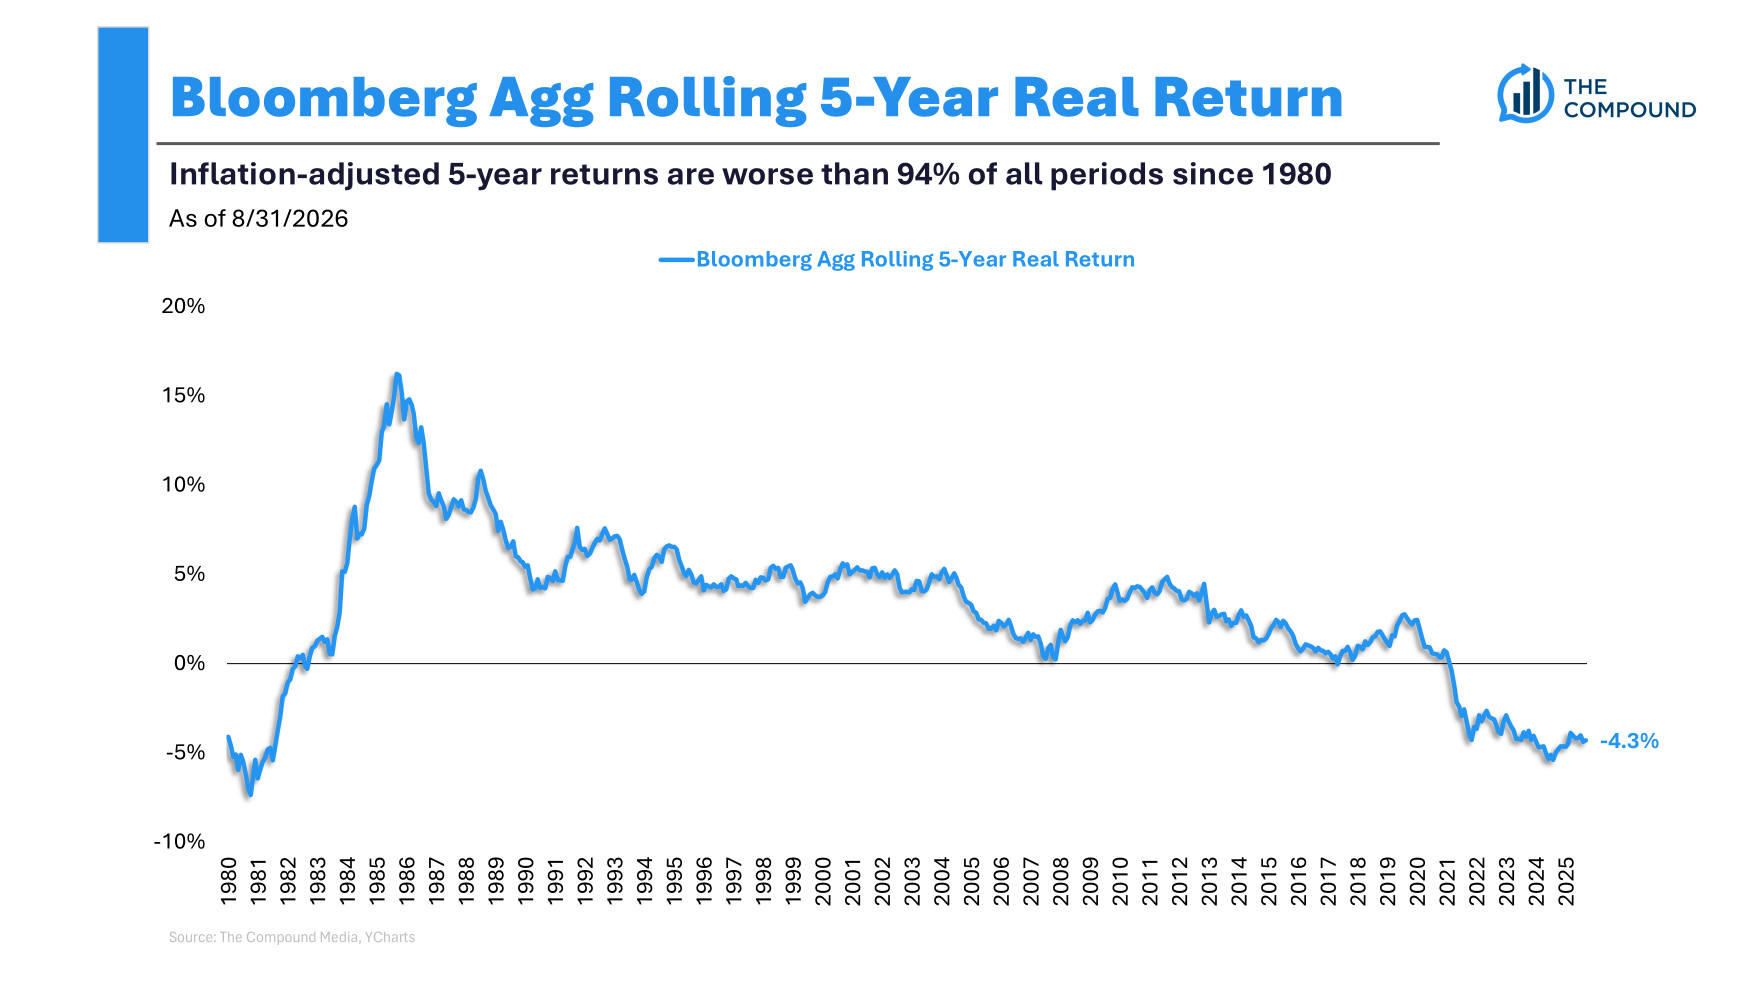
The only time 5 year real returns were worse than the current cycle was in the early-1980s when inflation was running in the double-digits.
The current 10 year real returns are as bad as they’ve ever been:
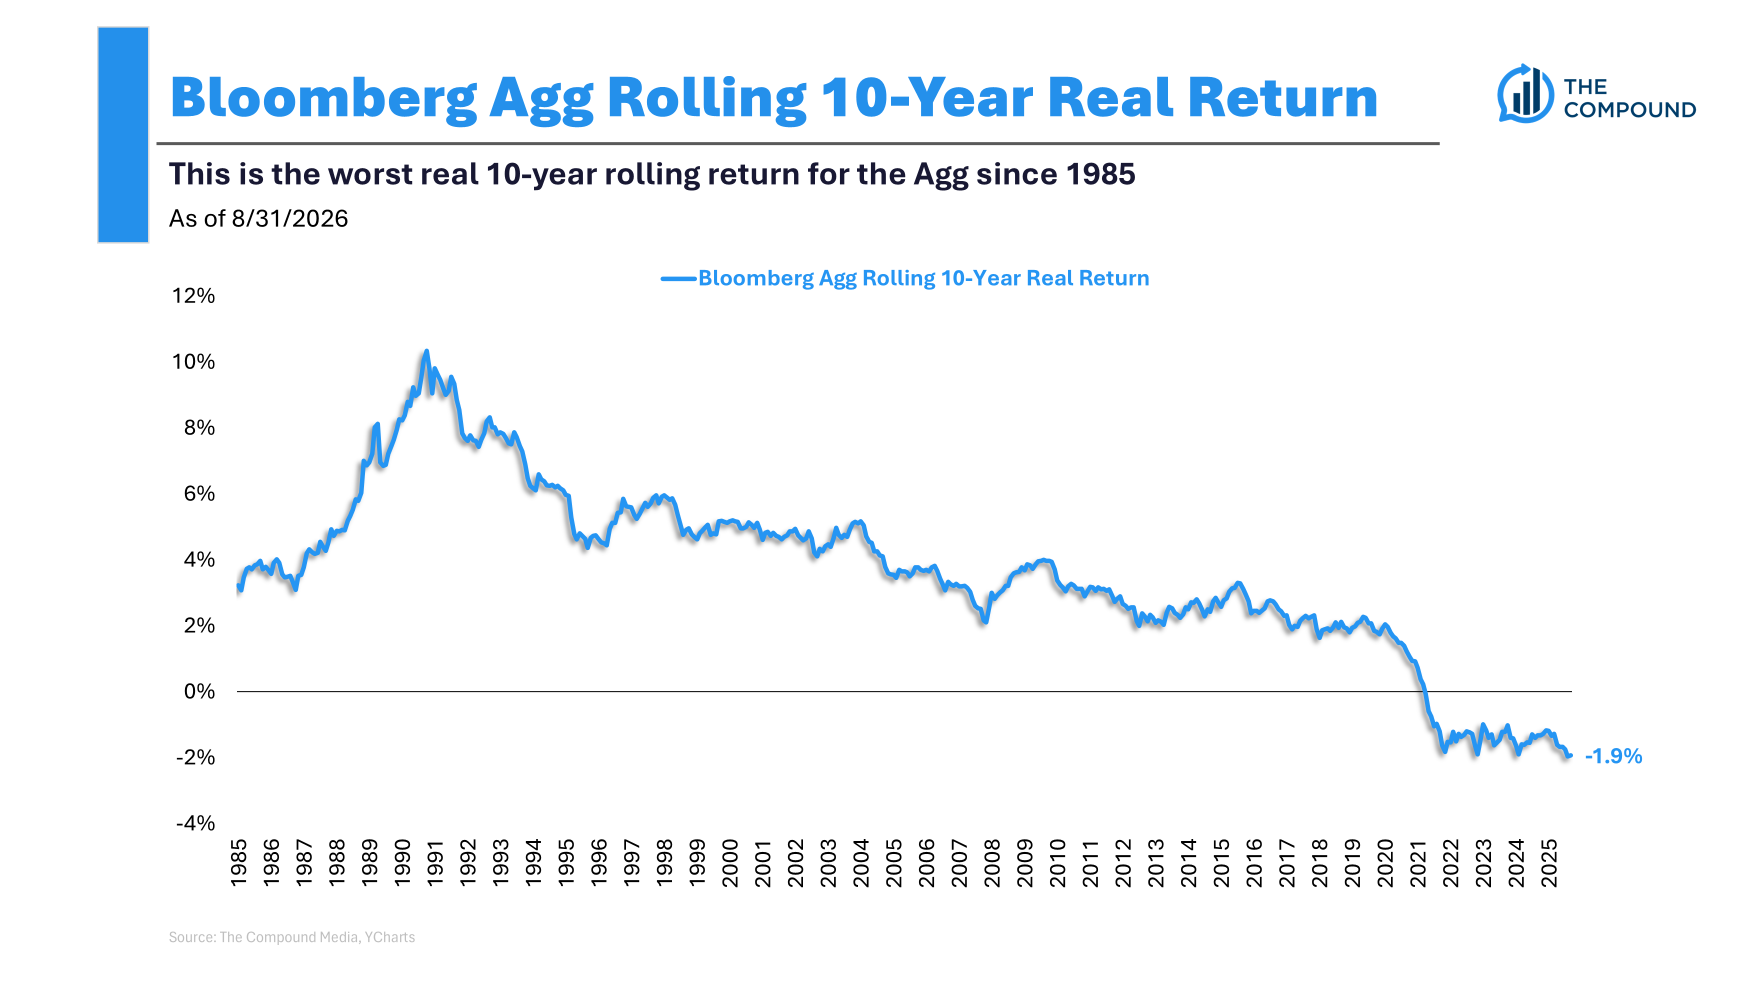
After inflation, it’s been a lost decade for quite some time now.
This is the most brutal bond market in modern finance history.
It’s no wonder bonds are the most hated asset class in the world.
There are a few reasons today’s bond market is even worse than what investors experienced in the late-1970s and early-1980s.
From 1976 to 1981, there wasn’t a single down year for the Agg. In fact, the first down year for the index didn’t occur until 1994 when it was down almost 3%.
The worst return in the late-1970s was in 1978 when the Agg was up 1.4%. This was nominal of course. Inflation was much higher back then than it is today. But the yields were much higher back then too.
In 2022, the Agg had its first ever double-digit down year when it fell 13%. 2021 (-1.5%) and 2022 (-13%) were the first back-to-back down years for the Agg in history.
And the bond bear market that began in 2020 when rates bottomed gave the Agg its worst drawdown in history:
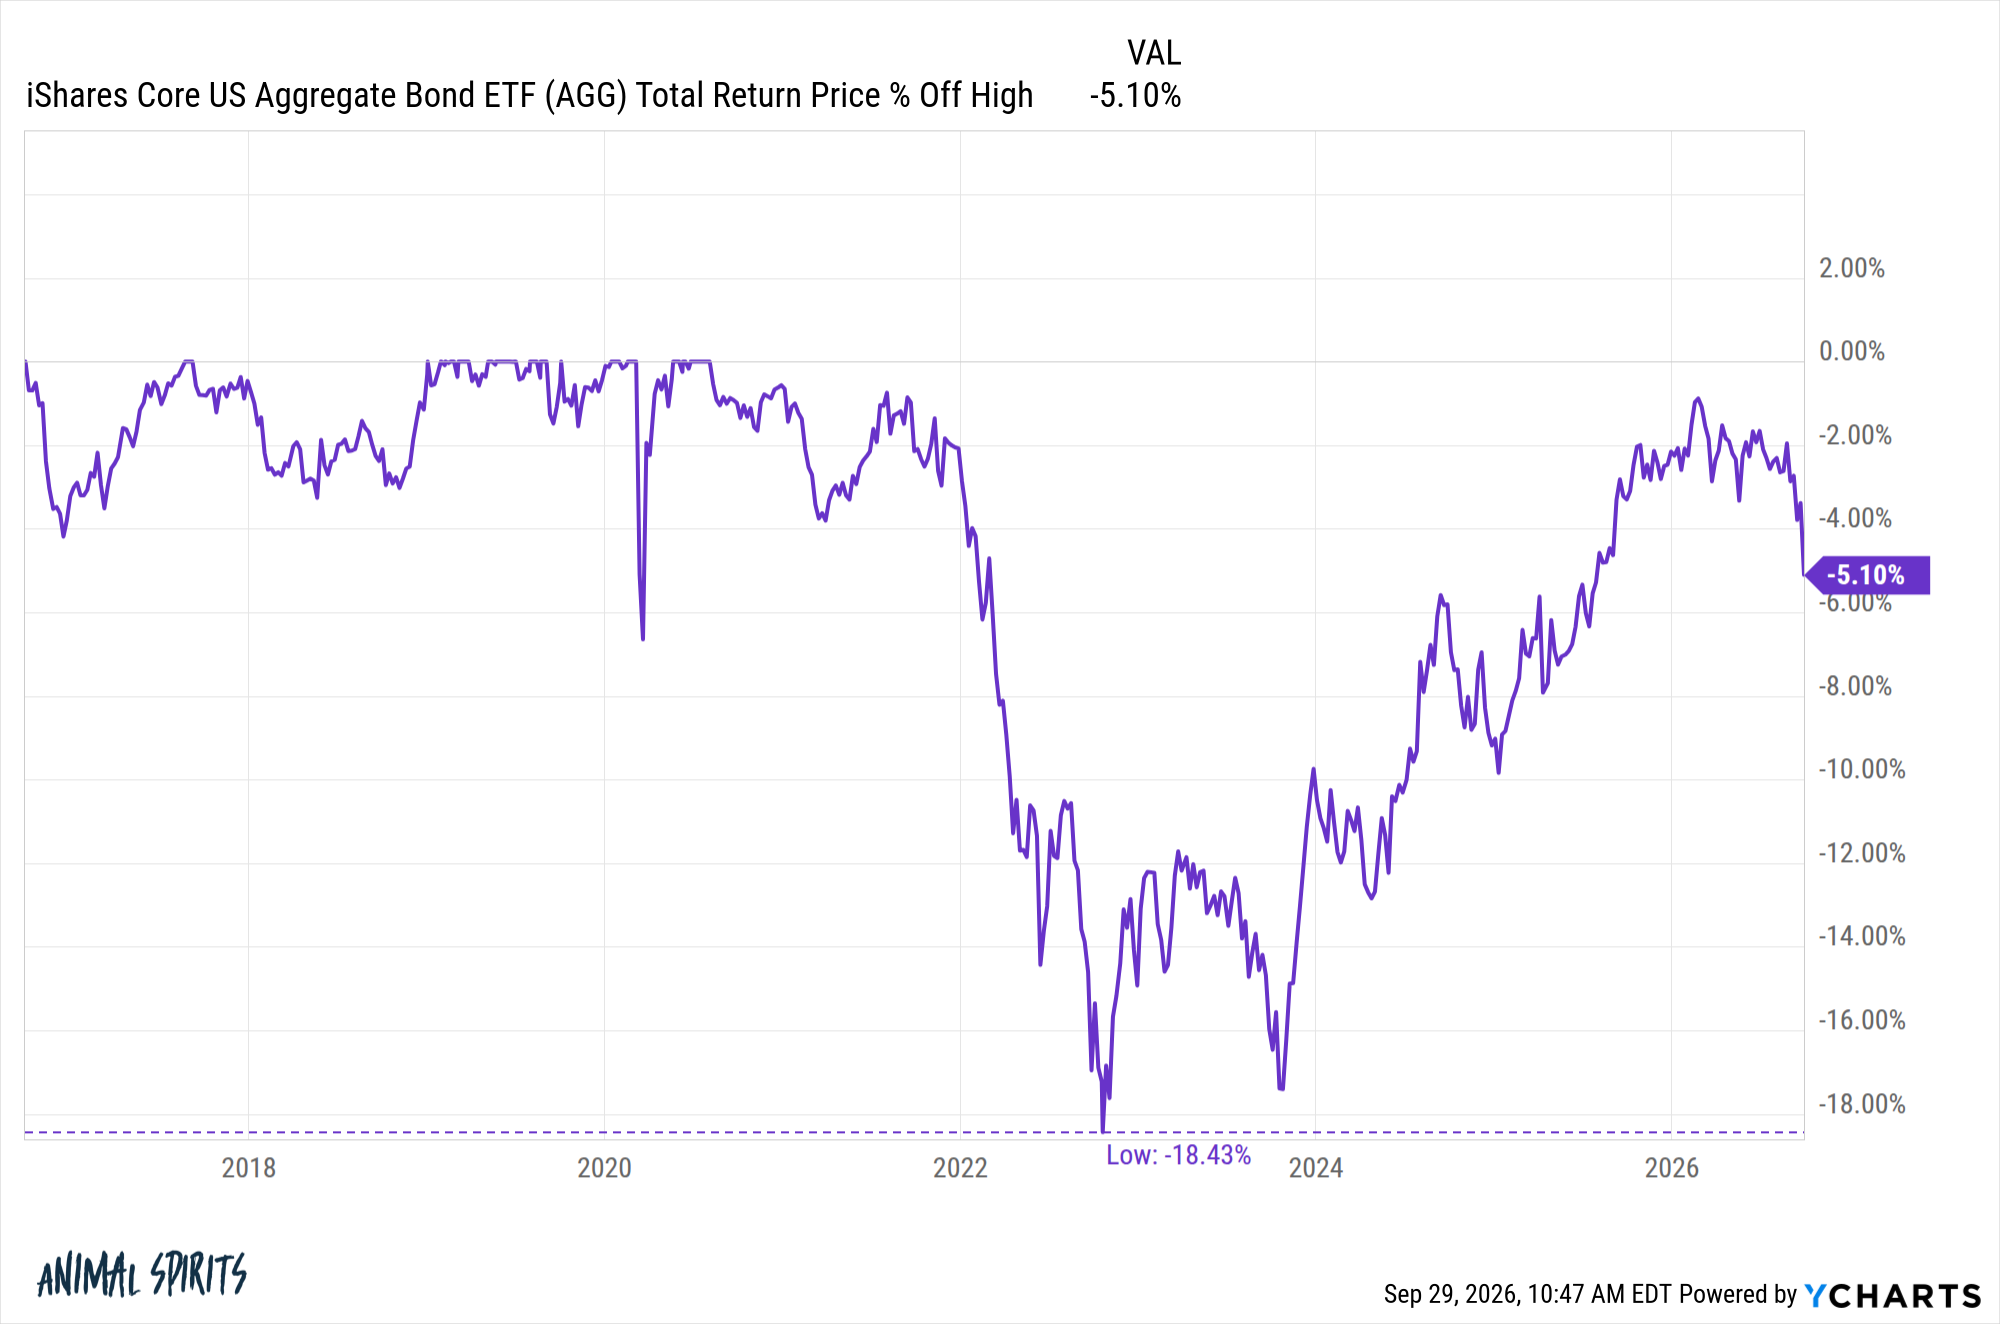
It was nearly a 20% decline which is basically unheard of in investment grade intermediate-term bonds.
The problem was threefold: (1) starting yields were too low, (2) interest rates shot up in a hurry and (3) inflation was high.
That’s a perfect storm for poor bond returns.
That’s the bad news.
The good news is that yields are now higher because bond investors just lived through a terrible period of performance.
The average yield to maturity for the Agg is now 5.5%. That’s a good thing for forward returns. You can see the relationship between the starting yield to maturity versus forward 5 year returns:
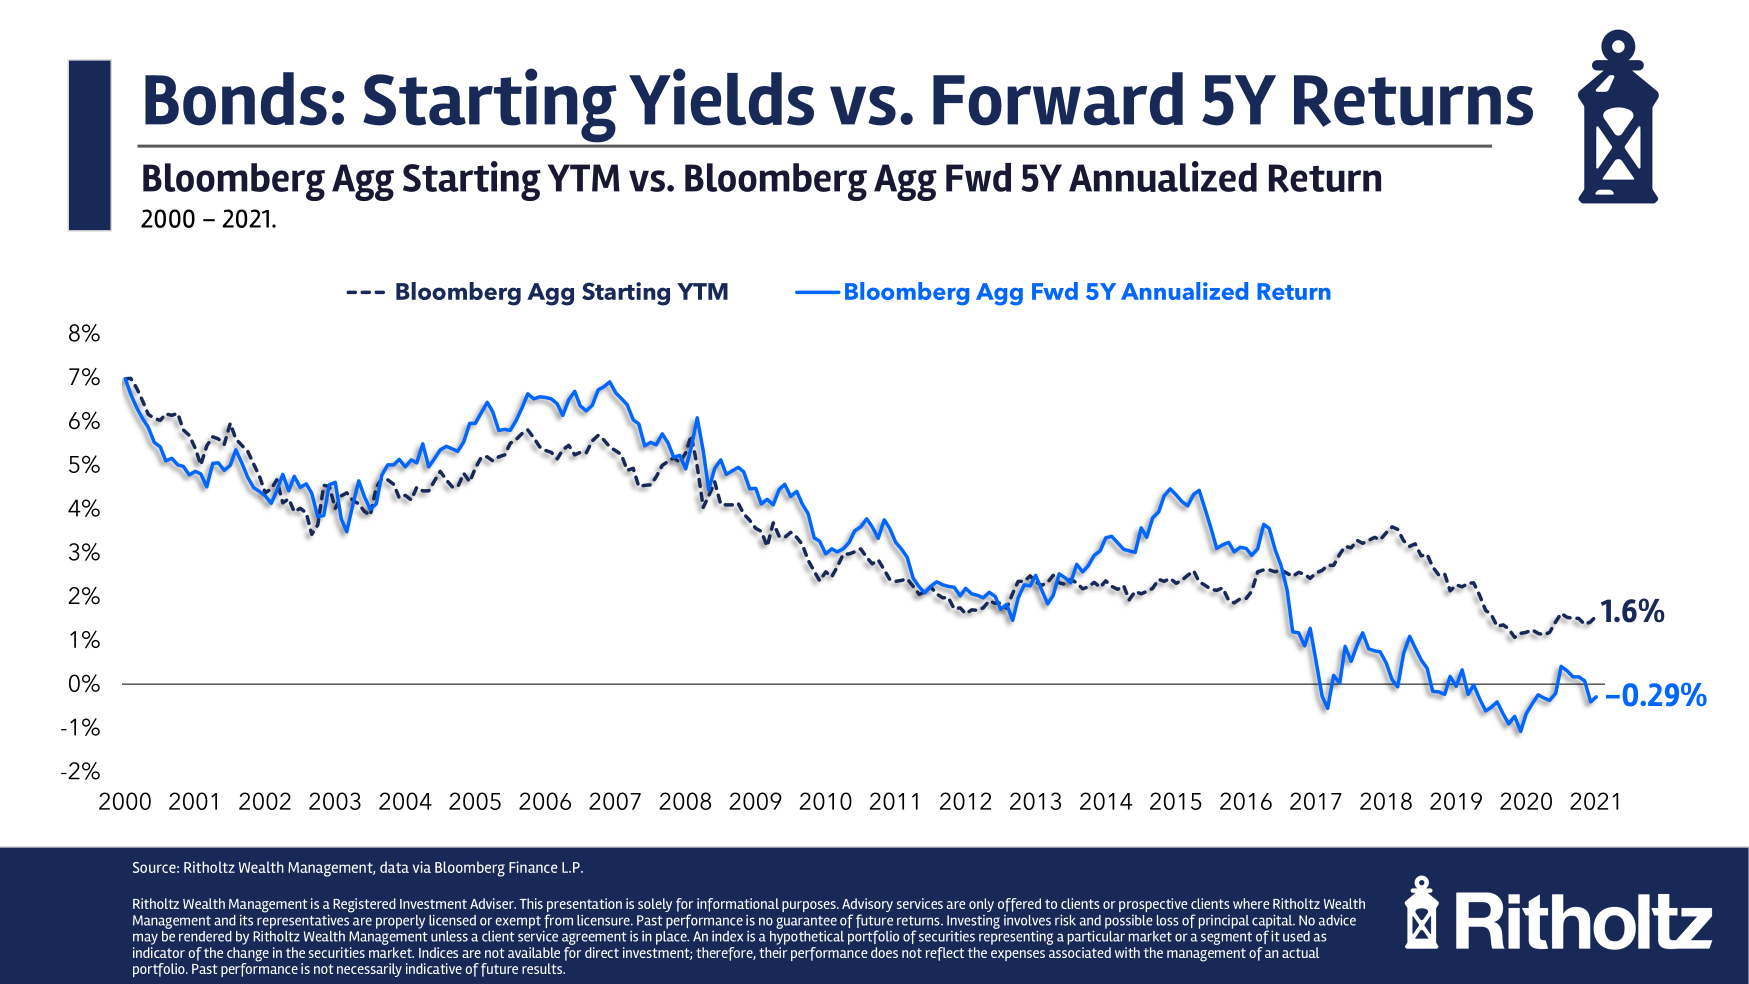
It’s interesting to note that the starting yield and forward return relationship broke down somewhat this decade. Interest rates rose so far so fast and yields were so low to begin with that returns have even underperformed the yield expectation.
So it’s actually been even worse than you think for bond investors.
That could change for any number of reasons:
- Inflation could fall.
- Economic growth could slow.
- We could *gasp* go into a recession (assuming we still have those).
- The AI trade could fall apart.
- The war in Iran could come to an end and energy prices fall.
It’s also true that interest rates could keep rising. Economic growth could remain strong. All of the AI spending could get even bigger. The war in Iran could drag on.
I’ve yet to encounter anyone in this field who has the ability to predict the direction or magnitude of interest rate moves. Even the Fed is not good at this.
Investors shouldn’t try to predict interest rate moves or macro developments when making fixed income decisions.
You should weigh the risk and reward of the various bond types by yield, credit quality, duration and maturity.
Cash yields are back up to 4%.
U.S. government bonds are yielding more than 5%.
The Agg is approaching 6%.
Corporate bonds yield more than 6%.
You can find even higher yields by taking even more risk.
This has been a lousy decade for fixed income investors unless you were sitting in cash or floating rate debt.
But yields are now at levels we haven’t seen in almost 20 years.
If rates go higher there will be some more short-term price pain. But that pain can now be offset by higher starting yields.
And the higher rates go, the higher forward returns expectations should go.
Further Reading:
The Most Hated Asset Class in the World
1This index has been called Lehman Brothers, Barclays and now Bloomberg. It’s like a stadium that keeps getting new sponsors.